Retired: What It Really Means Today (And How Online Selling Can Supercharge Your Retirement)
Introduction to Retirement
Retirement marks a major milestone in life—a period when you finally step away from your occupation and transition from earning a paycheck to relying on the resources you’ve built over the years. For many retired workers in the USA, this means shifting from a regular job to drawing income from savings, pensions, and Social Security benefits. The word “retired” itself signals a new chapter: you’re no longer working the same hours or facing the same daily demands, but you’re also tasked with making sure your money and resources last for the rest of your life.
The term "retired" generally means that an individual has stopped working permanently, often after concluding their professional career. Someone is considered retired when they permanently leave the workforce, typically stopping full-time employment to live off savings, pensions, or other income sources like Social Security. Most retired individuals in the U.S. are over the age of 65, although some may retire earlier or continue working into their 70s or 80s.
Take, for example, a couple planning to retire at age 65. They might expect to receive monthly Social Security payments, a pension from a former employer, and withdrawals from their retirement savings. But to determine whether their plan will truly cover their needs, they must consider factors like inflation, the risk of outliving their savings, and how many years they’ll need their money to last. Retired teachers often benefit from pensions that help cover expenses, but even they need to diversify their income sources to reduce risk and ensure long-term security.
As you approach retirement, you’ll hear a lot about the importance of having a solid plan. This means understanding your expected expenses, the benefits you’ll receive, and how to access resources like Medicare and Social Security. Applying for these benefits at the right time can make a significant difference in your financial situation. Building a comprehensive retirement plan—one that accounts for your family’s needs, community support, and potential challenges—can help you rest easy and enjoy this new phase of life.
Understanding the vocabulary and definitions around retirement is key. For instance, “pensions” refer to the pay retired workers receive from former employers, while “withdrawn” describes the act of taking money from your savings or retirement accounts. By learning these terms and how they apply to your situation, you become a more informed consumer, better equipped to make decisions that support your goals.
Retirement isn’t just about money—it’s about creating a life that brings you joy, security, and peace of mind. Whether you’re working with a team of financial advisors, accessing online resources, or leaning on family and community, taking the time to read, learn, and build your plan is one of the most important things you can do. With the right approach, you can make your retirement years some of the most rewarding and fulfilling of your life.
This guide is designed for individuals approaching retirement or already retired, as well as their families, to help them understand what retirement means today and how new opportunities like online selling can enhance their financial security and lifestyle.
Key Takeaways
- 01Being retired in 2026 means no longer relying on a traditional job for income—but not necessarily stopping work or earning entirely
- 02Most Americans retire between ages 59 and 67, combining Social Security, pensions, savings, and often side income
- 03Online selling platforms like eBay, Whatnot, Etsy, and Substack help retired workers stay mentally active, build community, and generate meaningful extra money
- 04Revolutionary Wealth helps clients integrate side-business income with tax strategy, retirement withdrawals, and Social Security timing
- 05A brief FAQ below addresses common worries about taxes, benefits, and time commitment
What Does “Retired” Mean in 2026?
The term "retired" generally means that an individual has stopped working permanently, often after concluding their professional career. Someone is considered retired when they permanently leave the workforce, typically stopping full-time employment to live off savings, pensions, or other income sources like Social Security.
The word retired once had a simple definition: you stop working, receive a pension, and spend your remaining years in leisure. Classic vocabulary around retirement described it as permanently withdrawing from your occupation after reaching a certain age.
That usage has shifted dramatically. In the USA today, typical retirement ages span 59 to 67, influenced by early access to retirement accounts at 59½, Medicare eligibility at 65, and full Social Security retirement age of 67 for those born in 1960 or later.
Several forms of retirement now exist. Retired teachers living on pensions differ from semi-retired consultants working 10 hours weekly. Ex-business owners drawing from portfolios while pursuing passions represent yet another category—financially independent but working by choice.
Being retired in 2026 often means liberation from trading time for money in a W-2 job. Many people choose selective projects for purpose and enjoyment. Revolutionary Wealth defines “retired” in practice as the year wage income stops and portfolio and pension income begin—a clear marker for planning.
Financial Life After You’re Retired: Income, Risks, and Taxes
Consider a 62-year-old who left work in 2024. She now lives on IRA withdrawals using a 4% safe withdrawal rate on her $1 million portfolio ($40,000/year), a $20,000 pension, and early Social Security at $2,000/month—totaling about $70,000 annually before taxes.
Major income sources for retired workers include Social Security, pensions (covering only about 15% of private-sector workers), IRA and 401(k) withdrawals, annuities, brokerage dividends, and supplemental side income.
Here’s where risk enters: sequence-of-returns risk means an early market downturn can permanently damage a portfolio. Studies show this risk is highest in the first decade of retirement, potentially reducing portfolio longevity by 5-10 years.
Taxes compound the challenge. A $120,000 lifestyle might require $150,000+ in gross withdrawals depending on your mix of pre-tax and Roth accounts. Adding $12,000-$30,000 in side income can meaningfully reduce reliance on taxable withdrawals, preserving Roth growth and lowering effective rates.
Why Bored Retirees Are Turning to Online Selling
Picture a 66-year-old corporate retiree in 2025, glad to be done with meetings—but restless after three months of unstructured days. AARP surveys show 52% of retirees cite lack of purpose as a challenge.
Non-financial motivations include mental stimulation, building community, learning new skills, and keeping up with technology. Studies suggest active engagement can reduce cognitive decline risk by 30-50%.
Financial motivations matter too: covering inflation (3-4% annually), funding family travel, helping grandchildren, or paying pre-Medicare health premiums ($500-1,000/month for those aged 59-64).
Unlike a rigid part-time job, online selling offers flexibility. You determine your hours, work from home, and scale seasonally—ramping up before Q4 holidays when sales can increase 2-3x.
Online Platforms Retirees Can Use to Sell and Earn
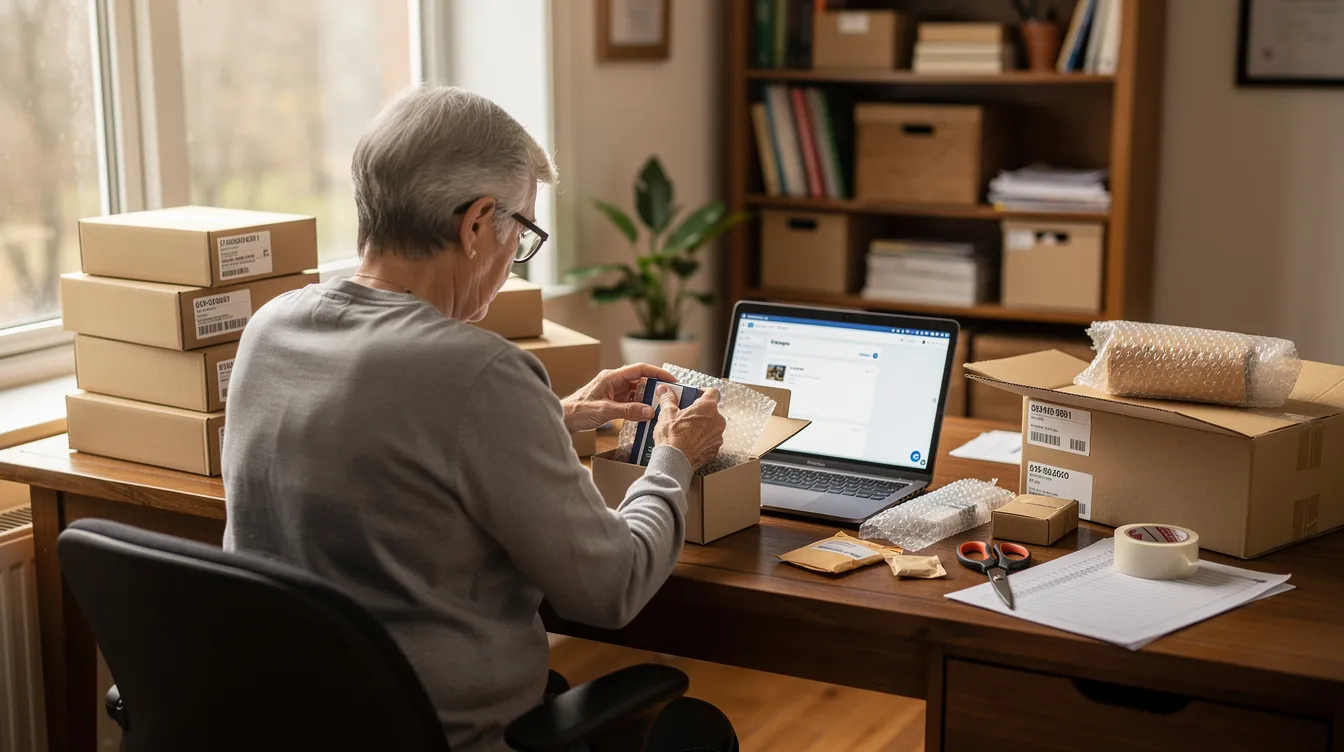
Below is a practical, platform-by-platform overview with 2024-2026 examples. Each has its own culture, fee structure, and ideal products. Start with one or two rather than all at once.
eBay: Turning Collectibles and Household Items into Cash
eBay remains ideal for downsizing retirees selling collectibles, vintage items, tools, and unused household goods. A 1980s baseball card collection might fetch $50-5,000; retired photography gear often sells for $100-1,000.
Sellers choose auction or “Buy It Now” formats, with fees in the 10-15% range. A retired engineer earned approximately $600/month in 2025 by liquidating decades of hobby gear and reselling estate-sale finds.
What you need: smartphone camera, printer, packing supplies, eBay account.
Whatnot: Live Auctions for Hobbyists and Collectors
Whatnot exploded between 2020 and 2024 as a live-stream selling platform for trading cards, comics, sneakers, and toys—reaching 10 million users by 2025.
A retired teacher hosts weekly 2-hour streams selling vintage Pokémon cards and 1990s comics, netting a few hundred dollars per show. The experience feels like hosting a weekly club—real-time chat fosters belonging and fun.
Requirements: stable internet, basic lighting, smartphone stand, quiet room. Fees run 8-10% plus payment processing.
Etsy and Handmade Goods: Monetizing Craft Skills
Etsy serves 96 million consumers seeking handmade goods, vintage items, and custom designs. Popular products include hand-turned wooden pens ($20-50), knitted baby blankets ($40-100), and custom jewelry ($15-200).
A retired nurse earns roughly $1,000/month selling custom graduation gifts each spring and holiday ornaments in Q4. Expect $0.20 listing fees plus 6.5% transaction fees—and invest in quality photography.
Amazon and Fulfillment by Amazon (FBA): Higher Volume, More Complexity
Amazon suits retirees with strong organization or prior business experience. The FBA model means sending inventory to Amazon warehouses, where they handle storage and shipping for 15-40% fees.
Examples include reselling wholesale home goods or publishing retirement guides via Kindle Direct Publishing. Be cautious: the learning curve is steep, and unsold inventory can mean 10-20% losses.
Substack and Digital Publishing: Earning from Your Expertise
Substack lets retirees monetize professional expertise through paid newsletters. A retired CPA writing tax-smart retirement content at $8/month with 200 subscribers generates $1,600/month gross before fees and taxes.
No physical inventory means this works well for retirees with mobility issues or limited space. Content ideas include travel guides for seniors, gardening tips, or financial education.
Other Useful Platforms: Facebook Marketplace, Poshmark, and More
Facebook Marketplace works for local furniture sales with zero fees—retired couples downsizing before moving to 55+ communities often share success here. Poshmark handles clothing (20% fees), while Mercari covers general goods (10%).
Local sales reduce shipping complexity but require safe porch pickups. These platforms suit one-time downsizing rather than ongoing businesses.
How Online Selling Fits into a Retirement Plan
Even an extra $1,000-$2,000 per month can materially change portfolio longevity. A 65-year-old with $1.5 million in investments could reduce required withdrawals from $90,000/year to $66,000/year thanks to $2,000/month net online income.
Side income can also allow delayed Social Security claiming—waiting from age 65 to 70 increases benefits by approximately 24%. That’s a significant boost to guaranteed income for life.
Revolutionary Wealth models different scenarios for clients using realistic tax rates, inflation projections of 2-3% annually, and healthcare costs, supported by a robust resource center of retirement, tax, and planning insights. The difference between plans with and without online income can be striking.
Tax Strategy for Retired Online Sellers
Online selling income is generally taxable as self-employment income if run as an ongoing business. This means Schedule C reporting and 15.3% self-employment tax on net profits above $400.
Online profits interact with Social Security taxation and Medicare premium brackets (IRMAA). Additional $20,000-$40,000 of profit could push you into higher premium tiers two years later, which makes using financial calculators and tax resources especially helpful when estimating net income and benefits impacts.
Common deductible expenses include:
Shipping costs ($5-20/item)
Platform fees (10-15%)
Home office (300 sq ft at $5/sq ft = $1,500/year)
Supplies and equipment
Example:$24,000 gross minus $6,000 expenses equals $18,000 net taxable income. Revolutionary Wealth coordinates with CPAs to integrate online income into broader strategies including Roth conversions and RMD planning beginning at age 73.
Risk Management, Time Commitment, and Lifestyle Fit
Not every retiree should build an online business. Fit with health, energy, and personal goals matters more than maximizing income.
Time commitment ranges:
Casual downsizing: 2-3 hours/week
Hobby-level selling: 5-10 hours/week
“Second career” business: 20+ hours/week
Physical considerations include lifting boxes and post office trips—mitigated by pickup services and ergonomic setups. Psychological risks include turning a beloved hobby into stressful work, so thoughtful lifestyle and financial planning should guide how large an online business you build in retirement.
Set boundaries: income targets, maximum weekly hours, and periodic reviews with a financial advisor ensure the business serves your life plan rather than dominating it.
How Revolutionary Wealth Helps Retirees Blend Work, Wealth, and Well-Being
Revolutionary Wealth is an independent financial advisory firm focused on pre-retirees and retirees, especially ages 59-67 and successful business owners exiting companies, supported by a dedicated team of retirement-focused advisors.
For clients launching online ventures, we provide cash-flow planning, tax optimization, and entity selection guidance (sole proprietor vs. LLC).
Side-business income connects to our broader resources: tax strategy, retirement withdrawal planning, fixed indexed annuities, and estate planning, all rooted in Revolutionary Wealth’s personalized wealth management approach. If you’re told an online venture might help your situation, we can evaluate whether your current plan supports it.
Frequently Asked Questions About Being Retired and Selling Online
Will selling online in retirement reduce my Social Security benefits?
If you’ve reached full retirement age (67 for those born in 1960 or later), earned income won’t reduce your Social Security check—though it can increase taxable income. Before full retirement age, earnings above $22,320 (2025 limit) can temporarily reduce benefits by $1 per $2 over. Read the rules carefully and coordinate with your claiming strategy.
How much can a typical retired person realistically earn from online selling?
Casual downsizers might earn a few hundred dollars monthly for 6-12 months. Committed hobby sellers often earn $500-$2,000/month after the first year. Six-figure businesses exist but require substantial time and risk tolerance. Start with a test-and-learn mind rather than banking your core retirement plan on aggressive assumptions.
Will an online business make my Medicare premiums go up?
Higher income from self-employment profits can push you into higher Medicare Part B and D premium brackets (IRMAA) two years later. For example, $20,000-$40,000 additional annual profit could increase monthly premiums by $50-300. Careful income timing and deductions, coordinated with an advisor, help manage this.
Do I need to form an LLC for my retirement side business?
Many retirees begin as sole proprietors, reporting income on Schedule C—adequate for low-volume selling. LLCs provide legal separation but introduce state fees ($100-800) and paperwork. Consult with a financial advisor and attorney before taking that step, especially if you have significant assets to protect.
What if I just want to be fully retired and not work at all?
That’s a completely valid choice. The priority is aligning money with the life you actually want—not maximizing every income opportunity. Revolutionary Wealth regularly builds plans for clients who prefer complete rest in retirement, using savings, pensions, Social Security, and tax-efficient strategies tailored to a work-free period of life, and offers educational retirement planning videos to help you understand your options before making big decisions.
Disclosures
This blog contains general information that may not be suitable for everyone. The information contained herein should not be construed as personalized investment advice. There is no guarantee that the views and opinions expressed in this blog will come to pass. Investing in the stock market involves gains and losses and may not be suitable for all investors. Information presented herein is subject to change without notice and should not be considered as a solicitation to buy or sell any security. Revolutionary Wealth LLC does not offer legal or tax advice. Please consult the appropriate professional regarding your individual circumstance. Past performance is no guarantee of future results.
Mutual Funds are sold by prospectus. Please consider the investment objectives, risks, charges, and expenses carefully before investing in Mutual Funds. The prospectus, which contains this and other information about the investment company, can be obtained directly from the Fund Company or your financial professional. Be sure to read the prospectus carefully before deciding whether to invest. An investment in the Fund involves risk, including possible loss of principal.
Rebalancing/Reallocating can entail transaction costs and tax consequences that should be considered when determining a rebalancing/reallocation strategy.
A REIT is a security that sells like a stock on the major exchanges and invests in real estate directly, either through properties or mortgages. REITs receive special tax considerations and typically offer investors high yields, as well as a highly liquid method of investing in real estate. There are risks associated with these types of investments and include but are not limited to the following: Typically no secondary market exists for the security listed above. Potential difficulty discerning between routine interest payments and principal repayment. Redemption price of a REIT may be worth more or less than the original price paid. Value of the shares in the trust will fluctuate with the portfolio of underlying real estate. Involves risks such as refinancing in the real estate industry, interest rates, availability of mortgage funds, operating expenses, cost of insurance, lease terminations, potential economic and regulatory changes. This is neither an offer to sell nor a solicitation or an offer to buy the securities described herein. The offering is made only by the Prospectus.
Diversification does not guarantee a profit or protect against a loss in a declining market. It is a method used to help manage investment risk.
Converting an employer plan account or Traditional IRA to a Roth IRA is a taxable event. Increased taxable income from the Roth IRA conversion may have several consequences including but not limited to, a need for additional tax withholding or estimated tax payments, the loss of certain tax deductions and credits, and higher taxes on Social Security benefits and higher Medicare premiums. Be sure to consult with a qualified tax advisor before making any decisions regarding your IRA.
Indexed annuities are insurance contracts that, depending on the contract, may offer a guaranteed annual interest rate and some participation growth, if any, of a stock market index. Such contracts have substantial variation in terms, costs of guarantees and features and may cap participation or returns in significant ways. Any guarantees offered are backed by the financial strength of the insurance company. Surrender charges apply if not held to the end of the term. Withdrawals are taxed as ordinary income and, if taken prior to 59 ½, a 10% federal tax penalty. Investors are cautioned to carefully review an indexed annuity for its features, costs, risks, and how the variables are calculated.
Not associated with or endorsed by the Social Security Administration, Medicare or any other government agency. Maximizing your Social Security Benefits assumes foreknowledge of your date of death. If as an example you wait to claim a higher monthly benefit amount but predecease your average life expectancy, it would have been better to claim your benefits at an earlier age with reduced benefits.
Please consider the investment objectives, risks, charges, and expenses carefully before investing in Variable Annuities. The prospectus, which contains this and other information about the variable annuity contract and the underlying investment options, can be obtained from the insurance company or your financial professional. Be sure to read the prospectus carefully before deciding whether to invest.
The investment return and principal value of the variable annuity investment options are not guaranteed. Variable annuity sub-accounts fluctuate with changes in market conditions. The principal may be worth more or less than the original amount invested when the annuity is surrendered.
QLACs cannot be purchased with Roth or Inherited IRA dollars; value of such IRAs cannot be included in determining 25% premium limit. If Funding Source is Traditional IRA, 25% limit is calculated by combining the total value of all Traditional IRAs as of December 31st of the previous year. If Funding source is Employer sponsored qualified plan (401k, 403b and governmental 457b), 25% limit is calculated on an individual plan basis based on the plan’s account value on the previous day’s market close. If you previously purchased a QLAC, the calculation of your 25% limit is more complicated. Please contact an attorney or tax professional for additional details. Any guarantees of the annuity are backed by the financial strength of the underlying insurance company.
The projections or other information generated by Monte Carlo analysis tools regarding the likelihood of various investment outcomes are hypothetical in nature, are based on assumptions that you provide which could prove to be inaccurate over time, do not reflect actual investment results, and are not guarantees of future results. Results may vary with each use and over time.
How we can help
Retirement Income PlanningA plan for turning what you've saved into money you can actually spend — in the right order, from the right accounts, without an unnecessary tax bill along the way.